- Consider ‘sticking it’ to The Flu: Flu shots seem to be available at practically every drug store or pharmacy in the St. Louis area. Discuss with your doctor the pros and cons of flu shots for yourself and your family.
- Get some zzz’s: The holiday hustle and bustle can interfere with normal sleep patterns, yet sleep is essential to health and healing. Prioritize getting enough sleep - or taking a quick nap - despite your busy schedule.
- Fill the fridge: It’s easy to allow your pantry to start looking like a sweet shop as the holidays near. Take care to stock your refrigerator and cabinets with healthy snacks and ingredients for balanced meals. Think fruit, nuts, lower-calorie snacks, veggies and lean proteins.
- Get real: Emotional health is important, too, so be realistic about what can be expected through the season. Just because it’s the holidays doesn’t mean that Aunt Zoe and Uncle Andrew will finally mend their rocky relationship.
- Keep moving: Despite the many holiday temptations to just relax, don’t give in to being a couch potato. Get to the gym or yoga studio, go for a walk in your neighborhood, jump on the treadmill or dance. The important thing is to just move!
Monday, December 12, 2016
Tips for a Healthy Holiday Season

Monday, October 3, 2016
Claims Quiz: Answers!
Did you take our claims quiz? Find the answers, and other helpful claims information, below...
1.) True or False: After an accident, it is best not to touch your vehicles or re-arrange anything about the way the cars are situated.
FALSE: After a crash, it is always best to move your vehicles and all people involved off the road. Unless there is an injury involved that requires that person to remain immobile, you are safer if they are off the road. Moving vehicles will not effect how the claim is processed and this is not considered "tampering with evidence".
2.) True or False: It is perfectly fine to take a picture of the other person's insurance card- no need to write it down.
TRUE: If it is easier, feel free to take a picture of the other person's insurance card. However, make sure it is saved safely and doesn't get deleted. Also, it is very important to make sure you have accurate contact information for the other involved party. You can also easily save this in your phone so you don't have to worry about finding a pen. You could call it at the scene to make sure it is accurate.
3.) True or False: If someone hits you and admits fault, it is imperative that you call your carrier and report the incident.
FALSE: If the other party is at fault, there is no need to get your carrier involved. If there is a discrepancy about fault or if the other carrier is not accepting fault, then getting your agent and carrier involved as advocates is a good idea.
4.) True or False: It is not necessary for you to speak with your carrier when reporting a claim. Your agent can completely report the claim for you.
FALSE: You must be the one to answer questions about the claim/ accident directly with your carrier. Your agent is here to help you along the process and be your advocate, but we cannot fully file the claim for you.
Other Helpful Auto Claims Tips
-Always call the police after an accident. They can write a report that may be helpful for the claims process.
-Where the accident occurred (be as specific as possible)
-How the accident happened
-What kind of vehicle or vehicles were involved (including the year,
make, and model)
-A description of the damage on each vehicle
-The names and contact information of people involved in the accident
-The extent of any injuries to people involved in the accident
-The names and contact information of anyone who witnessed the accident
-The name of the law enforcement agency that responded and the police
report number, if police were contacted
1.) True or False: After an accident, it is best not to touch your vehicles or re-arrange anything about the way the cars are situated.
FALSE: After a crash, it is always best to move your vehicles and all people involved off the road. Unless there is an injury involved that requires that person to remain immobile, you are safer if they are off the road. Moving vehicles will not effect how the claim is processed and this is not considered "tampering with evidence".
2.) True or False: It is perfectly fine to take a picture of the other person's insurance card- no need to write it down.
TRUE: If it is easier, feel free to take a picture of the other person's insurance card. However, make sure it is saved safely and doesn't get deleted. Also, it is very important to make sure you have accurate contact information for the other involved party. You can also easily save this in your phone so you don't have to worry about finding a pen. You could call it at the scene to make sure it is accurate.
3.) True or False: If someone hits you and admits fault, it is imperative that you call your carrier and report the incident.
FALSE: If the other party is at fault, there is no need to get your carrier involved. If there is a discrepancy about fault or if the other carrier is not accepting fault, then getting your agent and carrier involved as advocates is a good idea.
4.) True or False: It is not necessary for you to speak with your carrier when reporting a claim. Your agent can completely report the claim for you.
FALSE: You must be the one to answer questions about the claim/ accident directly with your carrier. Your agent is here to help you along the process and be your advocate, but we cannot fully file the claim for you.
Other Helpful Auto Claims Tips
-Always call the police after an accident. They can write a report that may be helpful for the claims process.
-This is the information you will need when reporting a claim:
-When the accident occurred-Where the accident occurred (be as specific as possible)
-How the accident happened
-What kind of vehicle or vehicles were involved (including the year,
make, and model)
-A description of the damage on each vehicle
-The names and contact information of people involved in the accident
-The extent of any injuries to people involved in the accident
-The names and contact information of anyone who witnessed the accident
-The name of the law enforcement agency that responded and the police
report number, if police were contacted
Tuesday, May 17, 2016
Make it a summer of giving back to the community
As your local independent insurance agency, we are a part of your community and we understand the need to support a variety of social service and community endeavors. Each month throughout the summer we are going to feature one of the ways Crawford-Butz gives back, either financially or through volunteer work, in our e-newsletter. We know our clients are active in the community as well. Share pictures of the ways you "give back" on our Facebook page through the end of June to enter a chance to win a $50 gas gift card for yourself and a $50 donation towards the organization you are serving. Hopefully you will be inspired, as we were, to get out in the community this summer and give back!To enter into the drawing for the giftcard and donation to a service organization of your choice, you must be a client of Crawford-Butz, visit and "like" our Facebook page, write a post or post a picture to our page showing how you volunteer or otherwise support the organization. The organization must be a non-profit that helps the greater St. Louis area in some capacity.
https://www.facebook.com/crawfordbutzinsurance/
All who post will be entered into the drawing, to take place on Friday July 1st at the main Crawford-Butz office. The winner will be contacted via Facebook.
To sign up for our monthly newsletter to see how Crawford-Butz gives back to the community please visit: http://www.crawfordbutz.com/sign-up
 |
| Crawford-Butz is donating to a summer camp for kids with autism and speech therapy needs for the second year in a row in 2016. |
 |
| Steve Butz with William Humphrey, the District Director of the Boy Scouts of America. Crawford-Butz has supported the Boy Scouts for a number of years. |

 |
| Autism Speak Walk 2015. Crawford-Butz was well represented on the Ajdin's Hope Team. |
Monday, February 15, 2016
Buying Life Insurance: It Isn't that Complicated
Part 1: Starting the Conversation
The most difficult part of buying life insurance seems to be actually picking up the phone and making the call to your agent. Once you have passed that hurdle, it just gets easier. According to LifeHealthPro there are over 18 million Americans who say they need life insurance, but do not have it.
In that initial conversation your agent will ask for a few pieces of basic information about you - your height, weight, age and tobacco use. This will easily give your agent the ability to generate quotes for you. This is a great jumping-off point to get into bigger discussions about what type (term or whole) and how much life insurance you need.
Monday, June 8, 2015
Umbrella Insurance: What you need to know
You have a retirement plan. This means you are ahead of the game, right? Or perhaps you are getting ready to send your kids off to college next year. You can finally sit back and relax, right? If you don't have an umbrella policy, don't get too comfortable. Getting hit with a liability lawsuit could put all your plans on hold.
Here is an example that happens all too often. You are in an auto accident and the other driver and passengers are seriously injured. The claim reaches $1.5 million and your liability auto insurance only covers $100,000. If you don't have an umbrella policy to extend that coverage, you will be responsible for $1.4 million. If you don't have that kind of money available, your assets will be seized. No one wants to have to rebuild their lives after something like that. However, umbrella insurance is one of the least known types of liability coverage.
In the event that a claim exceeds your underlying policy limits, a personal umbrella policy may be able to help by providing:
- Additional liability coverage from $1 million to $5 million for your primary and secondary homes, rental properties, automobile, motorcycle, watercraft, RV and more
- Coverage for most types of accidents - not just auto
- Legal defense fees not covered under your current auto policy
- Extended liability protection that helps protect your current assets and future earnings
Usually umbrella policies start at $1 million in coverage and are sold in million-dollar increments. You will also typically need to have minimum underlying liability limits on your homeowners and auto policies before you can buy an umbrella. To determine how many coverage you need, simply calculate your net worth by taking the value of your retirement and other assets and subtracting your debt.
The most important thing is to talk to your insurance agent. Call your agent directly or our main office at (314) 752-2500. Don't let something unexpected ruin what you have been working towards your whole life.
Monday, May 18, 2015
Crawford-Butz Sponsors World Pediatric Project Event
The World Pediatric Project (WPP) is a nonprofit humanitarian organization with a mission to heal critically ill children and build healthcare capacity in the world. While that sounds like a lofty goal and an overwhelming undertaking, they are doing it one child at a time.
On May 9th 2015 WPP held an inaugural event called Rock 'n Heal. Crawford-Butz was a gold level sponsor for this event and 10 members of the Crawford-Butz team were able to attend. The $2,500 that Crawford-Butz donated supports surgery for five children reached by WPP traveling medical teams! The party was held at the Jet Linx hangar at Lambert and included food, drinks and entertainment. Most importantly, however, is that fact that is raised $67,000 for the World Pediatric Project and is helping them to Heal a Child and Change the World.


On May 9th 2015 WPP held an inaugural event called Rock 'n Heal. Crawford-Butz was a gold level sponsor for this event and 10 members of the Crawford-Butz team were able to attend. The $2,500 that Crawford-Butz donated supports surgery for five children reached by WPP traveling medical teams! The party was held at the Jet Linx hangar at Lambert and included food, drinks and entertainment. Most importantly, however, is that fact that is raised $67,000 for the World Pediatric Project and is helping them to Heal a Child and Change the World.

Agent Matt Laux and CSR Jamey Moroney

One of the children that has received services through the World Pediatric Project was helicoptered in for the event

This little boy from Peru can now eat and breath without pain because of surgery he received through World Pediatric Project.

Monday, December 22, 2014
Auto Insurance: Smart phones make showing proof of insurance more convenient.
There are many among us who are familiar with needing to show proof of our automobile insurance, but for one reason or another we cannot find our ID card when needed. Yet today we all carry our smart phones or tablets wherever we go, and in most states an electronic version of your proof of auto insurance will satisfy the requirements for a proof of auto insurance coverage. It seems like such a trivial detail to remember to put our proof of insurance in an accessible location, but it is a detail that is often overlooked.
 New smart phones and insurance company apps have made keeping your necessary insurance documents conveniently accessible. Now whether you have been pulled over in a traffic stop or you are going to register a car, you can pull up a saved PDF of your proof of coverage and show proof instantly. We receive requests for duplicate auto insurance cards all the time. With the expansion of electronic forms becoming an acceptable proof of auto insurance; it has allowed us to better serve our clients by getting any necessary information passed to the correct party in a much more time efficient manner.
I would recommend that in addition to your physical proof of insurance that is sent by your auto insurance carrier. You might want to request an electronic version to sent to your phone in order to have fall back in the event your insurance card gets misplaced or damaged.
www.crawfordbutz.com
Thursday, December 4, 2014
Homeowners Insurance: Adding an alarm system is a cost effective way to provide basic home protection.
As insurance agents we are always looking for ways to add protection for clients. An alarm system installed in the home is a basic way to add some front line protection against burglary and fires, while also adding an overlooked discount on the homeowner's insurance policy. Most companies offer a discount on the homeowner's policy if a local or central station alarm system is installed. The discount for an active alarm system can vary depending on the insurance carrier and other discounts already in place, but in some cases the discount is substantial enough that it greatly underwrites the cost of the system.
 An alarm system can help mitigate some losses that could potentially be much worse. If a home break-in was to happen and an alarm system is in place, you might be able to limit the damage caused by the break-in, while removing the potential loss to your personal property inside the home. They are also helpful in alerting your fire protection service in the event that your home catches fire. Like a lot of things in life, if a home fire is caught early, the damage can be limited and may not result in a total loss to the home.
There are many types of home alarms available to consumers today. They can range from local systems where a physical alarm is sounded if someone attempts entry or if a fire starts, to central station alarms where your local emergency responders are alerted in the event of a break-in, smoke, or fire.
Please contact your insurance agent today to begin the discussion of how a home alarm system might be added, while learning about all the benefits available to you on your homeowner's insurance policy.
Kevin Butz
www.crawfordbutz.com
An alarm system can help mitigate some losses that could potentially be much worse. If a home break-in was to happen and an alarm system is in place, you might be able to limit the damage caused by the break-in, while removing the potential loss to your personal property inside the home. They are also helpful in alerting your fire protection service in the event that your home catches fire. Like a lot of things in life, if a home fire is caught early, the damage can be limited and may not result in a total loss to the home.There are many types of home alarms available to consumers today. They can range from local systems where a physical alarm is sounded if someone attempts entry or if a fire starts, to central station alarms where your local emergency responders are alerted in the event of a break-in, smoke, or fire.
Please contact your insurance agent today to begin the discussion of how a home alarm system might be added, while learning about all the benefits available to you on your homeowner's insurance policy.
Kevin Butz
www.crawfordbutz.com
Friday, September 5, 2014
Home and Auto Insurance: Why insurance is the perfect medium to touch people's lives.
Recently my wife and I had our fourth child, a daughter named Evelyn. Every time we have been pregnant we make an effort to go out a few times before the baby is born, which for us usually means sneaking out to an early movie or two. With this past pregnancy-induced movie binge we were able to catch the movie "Chef" starring Jon Favreau and Sofia Vergara. It is essentially a story about a successful chef who becomes fed up with having to satisfy the owner of his restaurant, and decides to strike out on his own. He comes to the realization that at his core he loves feeding people. He knows that when you feed someone well, you can literally feed their soul. Satisfying their need for a good meal can conjure feelings of comfort and satisfaction that very few experiences can replicate.
It is with this same sentiment that the agents and CSRs of Crawford-Butz handle our client's needs. At our core we know that when client's insurance needs are handled with all the care, experience, and knowledge we have, we have done our client's a great service. We take great pride in being well informed on the current trends in the insurance industry. We then use this knowledge to help better protect our clients. Our driving purpose is looking for gaps in coverage and ensuring that our clients are satisfied in the event a claim situation does arise. We are fueled when a client relays their satisfaction with our service or the auto and home insurance coverage we have provided.
This has been the mission of Crawford-Butz since the firm was formed by Norbert Butz in 1961, and excellent service to our clients and writing company partners continues to be our greatest motivation.
Tuesday, August 19, 2014
Auto Insurance: Keeping your auto insurance premiuim competitve by maximizing discounts and credits
Every
day we are bombarded with advertisements that claim you will be able to save
money on auto insurance if you switch from company A to company B. While in
some cases this is true, the advertisements do not tell you about the potential
hassle and potential negative
effects associated with switching companies. Insurance carriers try very
hard to keep their clients, and with that effort they instituted certain
credits and discounts that allow their clients to maximize the savings on their
auto insurance premium.
A well educated and professional auto insurance agent knows the various discounts and credits that a client
is eligible for. The discounts available to an auto insurance client can change
over the policy life of an insured, and it is very important to maintain a
relationship with your auto insurance agent to keep them aware of any major
life changes that could have an effect on the discounts available to you
the insured.
 A few of the more obscure discounts and credits
available are as follows:
·
Child away at school (more than 100 miles) without a car
·
Multi-car discounts (very important for newly combined
households)
·
Safe driver (accident or violation free)
·
Paid-in-full discounts
·
Electronic billing discounts
·
Longevity (the time you been with a carrier)
An annual or semiannual review of your auto insurance policy
with your agent can help ensure that you are continuing to get the best
possible auto insurance coverage for the best possible premium. As for myself
and all of the agents at Crawford Butz & Associates, we love hearing from
our clients and getting to know more about them. Every client’s situation is
unique and the more we know about our auto insurance clients, the better
we can serve them.
Tuesday, March 4, 2014
Making Smart Savings Choices
We are all looking for smart and easy ways to save money. Unfortunately,
sometimes this includes changing insurance coverages to extremely low levels or
eliminating coverage entirely. Before you make any drastic moves, read the
money-savings tips below and give Crawford-Butz Insurance a call (314)
752-2500.
Some information provided courtesy of Safeco Insurance.
• Review all possible discounts and credits with your agent: Most insurers offer a variety of policy credits
and account discounts that can translate into significant savings — without
endangering the level of protection you need for your home, autos and other
valuable property. And often, if you purchase multiple policies through the
same insurance company, you’ll receive further discounts. People who own
motorcycles or boats and who complete approved safety courses can qualify for
discounts, and families with teen drivers who earn good grades in school may
qualify for auto policy discounts.
• Increase deductibles for cost savings: Only a small
percentage of homeowners have claims in any given year, so you might consider
increasing your deductible.
• Full payment on policy: Depending on your financial
circumstances, you may be able to make lump-sum payments instead of partial
premium payments, such as monthly or quarterly. Partial payments often include
small transaction fees, so paying the full amount can eliminate those extra costs.
Saving money is important, but so is making sure that what
you’ve got is protected. If you’re looking for ways to save, or want to review your
coverages, give us a call!
Wednesday, October 9, 2013
Auto Insurance: Keep your contact and rating information up to date ensures proper customer service
Your auto insurance policy maybe the last detail you think of when contemplating all the factors involved in the moving process. As a homeowner or renter you have to remember to move the most vital pieces of your life, such as your cable service or internet account. This would also include remembering the myriad of other billing changes that make up the various aspects that keep your life running smoothly. Sadly though your auto insurance policy sometimes gets over looked when reorganizing your life.
One of the most basic ways to lift any confusion in providing you with best auto insurance customer service is to make every attempt at keeping your contact and address information up to date. A portion of your auto insurance rate is generated by your garaging address, and it can have an effect on the rate of your auto insurance coverage making the premium rise or fall depending on the new garaging location.
Another aspect effected by accurate location and contact information is claims service. By ensuring the garaging location and contact information on your auto policy is correct; you are taking the basic steps in ensuring that your claims adjuster will be able to handle claim in an efficient manner.
With the many facets involved in servicing an auto insurance policy it is very prudent to eliminate any barriers to service. By eliminating these barriers you are ensuring that you have done your part to streamline the service of the auto insurance policy, and thus creating a mutually beneficial relationship between yourself, your auto insurance agent, and your insurance carrier.

Friday, August 23, 2013
Auto Insurance: Understanding you liability coverages
Your auto insurance policy can be the first line of defense in covering your financial exposures in the event of an auto accident. The various areas of coverage on your auto policy extend coverage to very different areas of financial exposure. Bodily injury coverage is what most people think of when they think of the liability coverage on your car insurance policy. This portion of your car insurance policy is coverage that provides protection in the event that someone is subject to an injury resulting from your participation in an
accident.
 The areas of coverage on your car insurance policy include but are not limited to uninsured, underinsured, and medical payments. Uninsured and underinsured bodily injury are coverage areas that are often overlooked or not explained when a new policy is purchased or comes up for renewal. These areas of coverage award coverage to the party not at fault in an accident given that the other party does not carry an adequate coverage limit or possibly no coverage at all. In effect it is a liability coverage that covers the car insurance policy owner instead of another party. It is of paramount importance that attention be paid to these separate limits on your auto insurance policy; because if it were to ever happen that you would need to rely on these areas coverage you will be thankful a comprehensive limit was put in place.
Friday, August 16, 2013
Homeowner's Insurace: Protecting your college student's property while away at school.
Under home insurance contracts there are certain provisions provided for college student's property. Certain portions of their parent home insurance coverage is extended in event of a property loss while away at school. In most cases there is predetermined limit for the extended coverage, and is usually 10% of the personal property limit on the primary home insurance policy. For example, if you currently carry $150,000 of personal property coverage on your home insurance policy the limit for your college student's property would be $15,000.
In addition to the personal property coverage being extended to your college student's property; you can also add a property schedule for higher value items such as a laptop computer to the primary home insurance policy. When these items are scheduled it awards more comprehensive coverage to the listed items, which in most cases can mean agreed value coverage (retail purchase price) in stead of actual cash value coverage in the event of a loss.
 Your home insurance policy is not the only policy effected by your student moving away to school. You will want to inform your insurance agent of the move to allow them to endorse your auto policy with the appropriate rating changes. There are different effects to policy if your student takes a vehicle to school as opposed to them leaving the car behind. In all cases you will want to leave your student on the policy as they will still be considered a listed driving member of the household.
Friday, July 19, 2013
Auto Insurance: Increased liability limits can be your first line of defense.
When you begin to have the auto insurance coverage limit conversation with your current, or potentially new insurance professional; a large emphasis should be placed on the bodily injury, underinsured, and uninsured coverage limits you are placing on your auto insurance policy.
 These three auto insurance coverages are your front line protection in the event you are involved in auto accident where injuries have occurred. The bodily injury coverage on your auto insurance policy is the coverage that protects you in the event you injure another motorist, while the underinsured and uninsured coverage on your auto insurance policy gives you a personal level of protection in the event the other motorist is deemed at fault and is not adequately insured.
Writing adequate levels of protection on your auto insurance policy should be the number one priority of any prudent insurance professional. The price difference between higher and lower limits of coverage on your auto insurance policy is sometimes smaller than you might think, and can easily be endorsed onto an existent auto insurance policy . If you are currently satisfied with the service you are being provided by your insurance carrier and agency, than a simple policy review and endorsement quote can tell you any additional premium difference it would cost to increase the liability limits on your existent policy.
These three auto insurance coverages are your front line protection in the event you are involved in auto accident where injuries have occurred. The bodily injury coverage on your auto insurance policy is the coverage that protects you in the event you injure another motorist, while the underinsured and uninsured coverage on your auto insurance policy gives you a personal level of protection in the event the other motorist is deemed at fault and is not adequately insured.Writing adequate levels of protection on your auto insurance policy should be the number one priority of any prudent insurance professional. The price difference between higher and lower limits of coverage on your auto insurance policy is sometimes smaller than you might think, and can easily be endorsed onto an existent auto insurance policy . If you are currently satisfied with the service you are being provided by your insurance carrier and agency, than a simple policy review and endorsement quote can tell you any additional premium difference it would cost to increase the liability limits on your existent policy.
Monday, June 17, 2013
Homeowners Insurance 101
The spring is shaping up to be another year full of storms and with them home insurance claims will follow. Many home insurance carriers are beginning to take a long and hard look at the way they write insurance contracts. In some instances home insurance carriers are moving to a percentage of dwelling deductible instead of fixed dollar all peril deductible. For example if your home is insured for $220,000 and your carrier moves to 1% deductible, you could be exposed to a potential $2,200 out of pocket deductible.
Changes of this nature are going to become more common in the foreseeable future as insurance carriers attempt to recoup losses that have them operating at a loss since the tragedies in Joplin, MO and Hazelwood, MO.
Be sure that you make time to review your home insurance coverages on your home insurance policy with your agent. This will help to ensure your are purchasing the most comprehensive coverage you are able to obtain.
 The changes to home insurance policies are not as devastating as you might think, but the changes are definitely worth having a conversation about. Mainly because it will make some insured change the way the look at their home insurance coverage, and re-explore the true purpose of their home insurance coverage.
Friday, May 31, 2013
Home Insurance:June is Still Peak Tornado Season: Are you Ready?
The country has already
suffered severe damage and devastation from storms and tornados this year. The peak season for
tornados in the midwest is actually March through June. Are you prepared? Do you know what to do before and after
the storm hits?
Missouri is considered at high
risk for tornados and is in "tornado alley," which places the state in the top
five for tornado activity. Tornado damage is covered by your basic home
insurance policy under wind damage, but it is important to know what to do after
the tornado to make a claim and ensure the most smooth payoff. Of course the
most important thing is the safety of your loved ones. Once you know everyone is
safe, follow the steps below so you are prepared to make your claim.
A few other helpful tips:
As always, it is best to go over
your specific home policy with your agent. Call the Crawford-Butz office at
(314) 752-2500 with any questions or concerns. We are here to serve you and your
family this tornado season and always!
| |
Wednesday, May 29, 2013
Home Insurance: Certain water losses could be potentially uncovered by your home insurance policy
When you are shopping for a new home insurance policy, or doing a review of your home insurance policy with your agent there are few water specific coverages you may want to consider endorsing onto to your home insurance policy. Certain ground and sewer water losses can be a non covered loss on a basic home insurance contract, and separate coverage could potentially need to be endorsed onto to your home insurance policy in order to guarantee coverage.
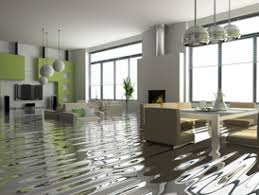 1) Sewer and sump pump overflow is a coverage that is often times over looked, but can prove to invaluable in terms of having your home insurance policy cover losses to major household item stored in your basement. Homes that are built on a slab foundation, or split level homes, as opposed to a basement should pay particular attention to this coverage as the backup will occur not in your basement but on your first floor living space.
2) Groundwater not generated by the overflow of a sewer or sump, but instead generates and enters the home at the surface level needs to protected by a flood insurance policy. Ground water generated losses are excluded on almost all home insurance policies, but can easily be covered by buying a separate flood insurance policy through your agent. Homes located in designated flood plains will of course carry a higher premium, but for homes located outside of the designated flood plains these policies can be relatively inexpensive.
2) Groundwater not generated by the overflow of a sewer or sump, but instead generates and enters the home at the surface level needs to protected by a flood insurance policy. Ground water generated losses are excluded on almost all home insurance policies, but can easily be covered by buying a separate flood insurance policy through your agent. Homes located in designated flood plains will of course carry a higher premium, but for homes located outside of the designated flood plains these policies can be relatively inexpensive.
Tuesday, May 28, 2013
Renters Insurance
If you live in a rental home or apartment, chances are you don't have the proper insurance. Despite the fact that rented homes are more likely to be burglarized than owner-occupied properties, nearly 60 percent of renters don't have a renters policy.
What does it matter? "If you rent a house or apartment and think that your landlord is financially responsible when there is a fire, theft or other catastrophe - think again," warns the Insurance Information Institute. "Your landlord's policy won't replace your personal possessions or pay for your living expenses while the building is being repaired. The only way to protect your self financially against disasters is to buy a renters insurance policy." Renters insurance covers your possessions, liability and additional living expenses.
Possessions
Standard renters insurance protects your personal belongings against damage from fire, smoke, lightning, vandalism, theft, explosion, windstorm, water and some other possible catastrophic events. Similar to a homeowners policy, earthquakes are not covered, however they can be added through an endorsement to your policy. If your rental unit provides storage space in a basement, you may want to consider coverage for water and sewer backup. Talk to your agent to make sure you have the coverage you need.
Liability
According to Safeco Insurance, standard renters insurance policies also provide liability protection in the event you or members of your household cause injury to others or damage their property. It may also pay for damage your pets cause. According to an article by Safeco Insurance, if you are sued, the liability portion of a renters policy may pay for both the cost of defending you in court and for court awards, up to the limit of the policy.
Additional Living Expenses
Many people are pleasantly surprised to learn that Additional Living Expenses (ALE) coverage is typically included in a renters insurance policy. If the home or apartment you are renting is damaged or destroyed and you need to live elsewhere while it is being repaired or rebuilt, renters insurance will cover your additional living expenses- namely the difference between your regular living expenses and the additional costs incurred by having to live away from your home, such as hotel bills, temporary rentals, restaurant meals, etc...
If all of this has gotten you thinking about looking into a rental policy give us a call to discuss it today! 314.752.2500
The information in this article was provided courtesy of Safeco Insurance.
Thursday, May 23, 2013
Auto Insurance: Steps you should take in the event of an accident
When someone is involved in an automobile accident with another driver, there are a few simple steps you can take to ensure the claims process will be handled by your auto insurance carrier in a efficient and effective manner.

1) Call a police officer: Even if the damage or accident is minor a police officer can assist in the exchange of correct auto insurance and personal information. There is no express need to take photos of the other vehicle or your own vehicle, as adjusters will be completing a valuation of the fault and damage.
2) Call your auto insurance company's claim number as soon as is feasible. The initial contact to your auto insurance company does not have be from the side of the road, but the sooner you report the incident the sooner the claims process can begin. Your auto insurance company can also direct you to any resources you might need such as a rental vehicle or tow service.
3) Call your auto insurance agent. They have a vested interest in your account and overall client satisfaction. They can prove to be a great sounding board and advocate in what can be a confusing situation.
Subscribe to:
Posts (Atom)